Accepting WeChat Pay and Alipay as an Overseas Business
Chinese consumers don't pay with cards. Here's how cross-border WeChat Pay and Alipay acceptance actually works for foreign businesses — setup, settlement, fees and the pitfalls to avoid.
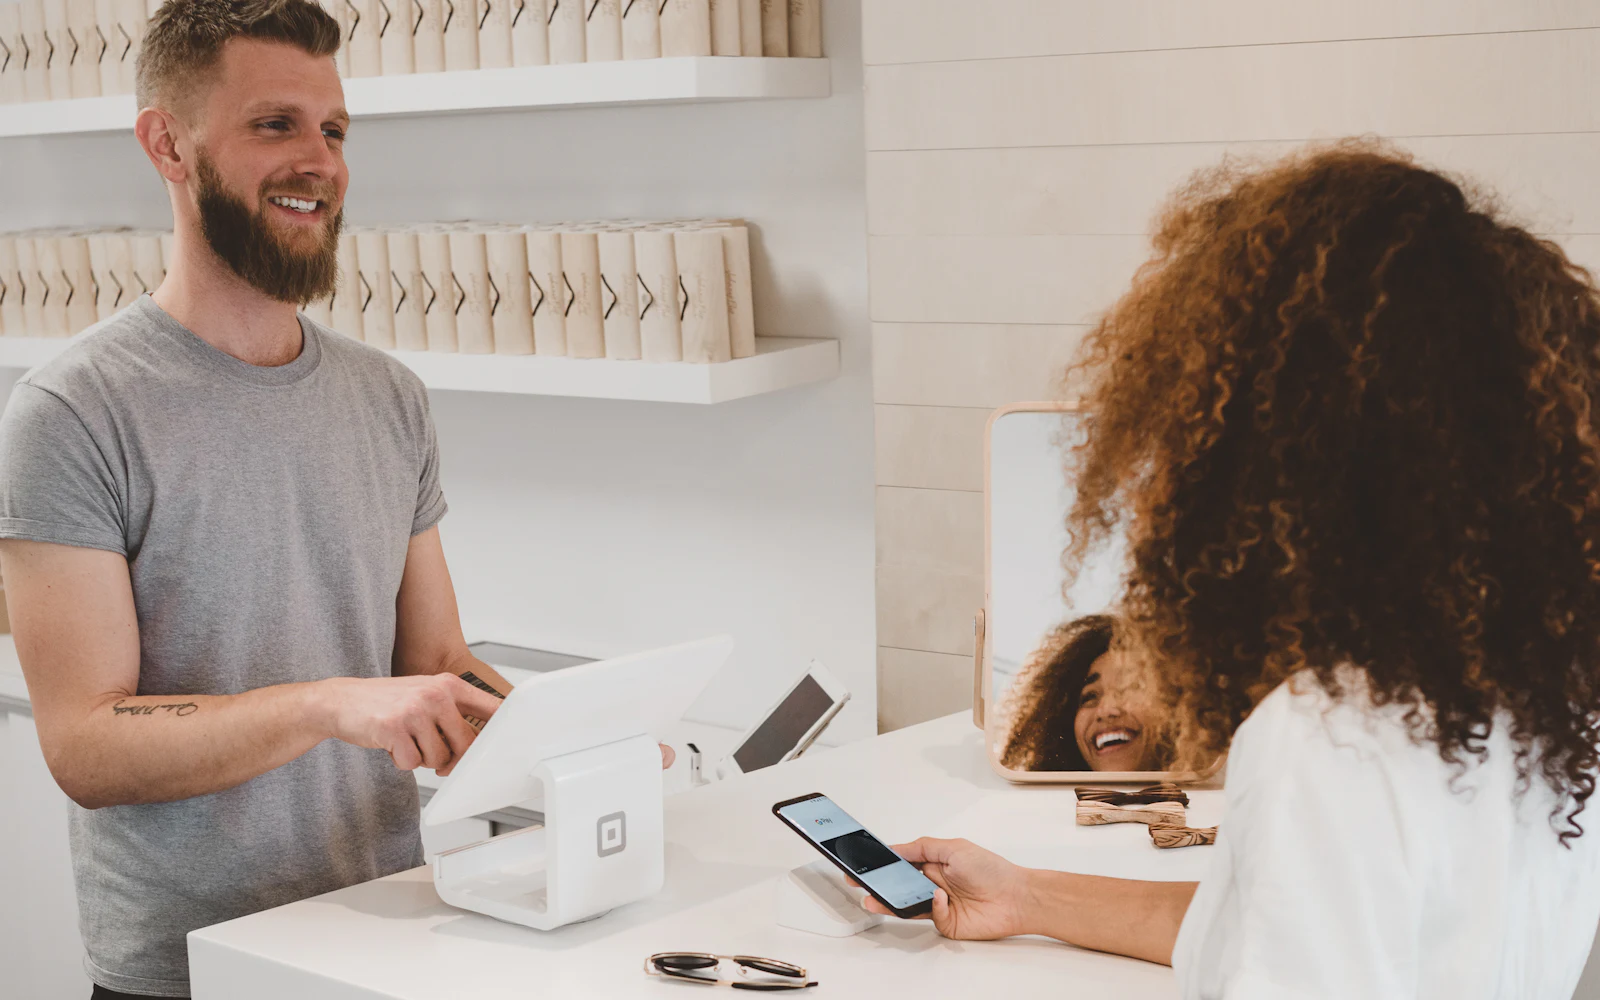
For most overseas businesses, the China opportunity doesn't die at marketing — it dies at checkout. You can win the discovery battle on Xiaohongshu and Douyin, get a motivated buyer to your booking page, and then watch the order evaporate at a form that asks for a credit card number. It isn't that Chinese consumers can't pay you; it's that you're asking them to pay in a way they simply don't use.
At home and abroad, Chinese consumers pay with two mobile wallets: WeChat Pay and Alipay. Scanning a QR code or confirming an in-app payment sheet is the default for everything from street food to five-figure purchases. International credit cards are the exception, not the rule — and a foreign-currency card form signals friction and risk to a buyer who has never needed one.
The short version: you don't need a Chinese company or a Chinese bank account. Cross-border merchant programs let an overseas business charge customers in RMB and settle in your own currency — online, inside a WeChat Mini Program, or at your front desk.
The two rails
- WeChat Pay lives inside WeChat, which makes it the natural rail when your storefront is a WeChat Mini Program — checkout never leaves the conversation where the recommendation happened.
- Alipay is a standalone super-app with deep roots in commerce and travel, and its cross-border acceptance network is mature and widespread among overseas merchants.
In practice you'll want both. The application documents overlap almost entirely, and accepting one but not the other means turning away real buyers at the counter.
The three ways to accept
1. In-store QR payments
The customer scans your code, or you scan theirs, and the payment confirms in seconds — in RMB, from the wallet they use every day. For hotels, attractions, clinics, restaurants and retail, this is the fastest win and needs no product build at all.
2. Inside a WeChat Mini Program
Native in-app checkout is the highest-converting option: browse, book and pay without ever leaving WeChat. It requires a Mini Program connected to a merchant account — and note that the legal entity behind both must match, which is one of the most common setup mistakes. (New to Mini Programs? Start with our Official Account vs. Mini Program guide.)
3. On your website or app
H5 and in-app payment flows redirect the buyer into their wallet to confirm. They work, and they're the right choice when your existing web funnel matters — but expect more drop-off than a native Mini Program flow.
How cross-border settlement works
The mechanics are simpler than most merchants expect:
- You price and charge in RMB at the point of sale.
- The scheme (or your payment partner) handles currency conversion.
- Funds settle to your existing business bank account in a supported major currency — USD, EUR, GBP, JPY, KRW, AUD, NZD and others — on a regular cycle.
Refunds are handled through the same channel via API or dashboard, and the dispute model is materially calmer than card networks — there is no card-style chargeback system, which for tourism and services businesses removes a whole category of headache.
What setup actually requires
Onboarding is a documentation review, not an engineering project. Most overseas businesses apply through a licensed payment partner (which speeds approval and simplifies compliance) and provide:
- Business registration documents for your entity
- The legal representative's ID
- Business bank account details for settlement
- Evidence of what you sell — your website, store photos, or booking materials
- Your business category, which is reviewed against each scheme's rules
Two things to know before you apply. First, regulated categories get extra scrutiny: medical services (including medical aesthetics), healthcare products and similar sectors need additional qualification documents, and approval is case by case — prepare the paperwork before you apply, not after a rejection. Second, thin evidence stalls applications; a half-finished website with no visible products is the most common cause of delay.
With documents in order, expect the process to take days to a few weeks, and plan it in parallel with your storefront build rather than after it.
Fees, in plain terms
Cross-border acceptance costs a per-transaction fee in the low single digits, varying by market, category and partner, with currency conversion applied at settlement. There are typically no meaningful fixed costs, so it scales with actual sales.
For context: tourism operators routinely pay OTA commissions that run well into double digits for bookings they don't own the customer relationship on. A direct channel with wallet payments isn't just better economics per transaction — it's your customer, your data, and your repeat booking.
Common questions
Do I need a Chinese legal entity? No. Cross-border programs exist precisely so overseas entities can accept these payments with local business documents.
Do I need a Chinese bank account? No. Settlement arrives in your home currency to your existing business account.
What does the customer experience look like? RMB pricing, the payment sheet they use every day, done in seconds. No card numbers, no foreign-currency surprise on their statement.
Can we take deposits and balances? Yes — deposit-plus-balance and partial-refund patterns are standard and well supported, which matters for tours, clinics and bookings with cancellation windows.
Pitfalls to avoid
- Entity mismatch between your Mini Program and your merchant account — the classic launch-week blocker.
- Applying with thin evidence of your business. Make the reviewer's job easy.
- Regulated category surprises. If you're in a category that needs qualifications, confirm the document list first.
- Set-and-forget RMB pricing. Review your prices against FX drift on a schedule, or your margin quietly erodes.
- Treating payments as the last step. Payment flow shapes the whole booking experience — design it into the storefront from day one, not as a bolt-on.
Where CN1X fits
Payments are one layer of the channel we build: CN1X handles merchant onboarding, connects WeChat Pay and Alipay to your Mini Program storefront, and operates the funnel that fills it — end to end. If you want to know what acceptance would look like for your business and category, ask us directly; it's a short conversation.
More from the blog
Korean and Japanese Operators Selling into China
A short flight changes the customer. What long-haul advice gets wrong for operators in Korea and Japan, and which barriers you have already cleared.
What a Month of Running the Account Actually Looks Like
"What is the ongoing commitment" is really a question about calendars. Where the hours land, who they land on, and which parts cannot be batched.
What You Supply Before a Mini Program Build Starts
The quote is signed and then three weeks pass with nothing visible happening. Almost always the build is waiting on things only you can hand over.